
 PAYROLL LINE OF CREDIT
Payday doesn't wait on invoices.
Draw what you need for payroll from a Loot line of credit, $5,000 to $100,000. Pick how often you repay, and clear it early once your client pays.
 Instant decisions on requests up to $30K
 Soft pull to apply
This is for businesses open a year or more with at least $12K a month coming into the business account.

It takes under five minutes, and checking won't touch your credit score.
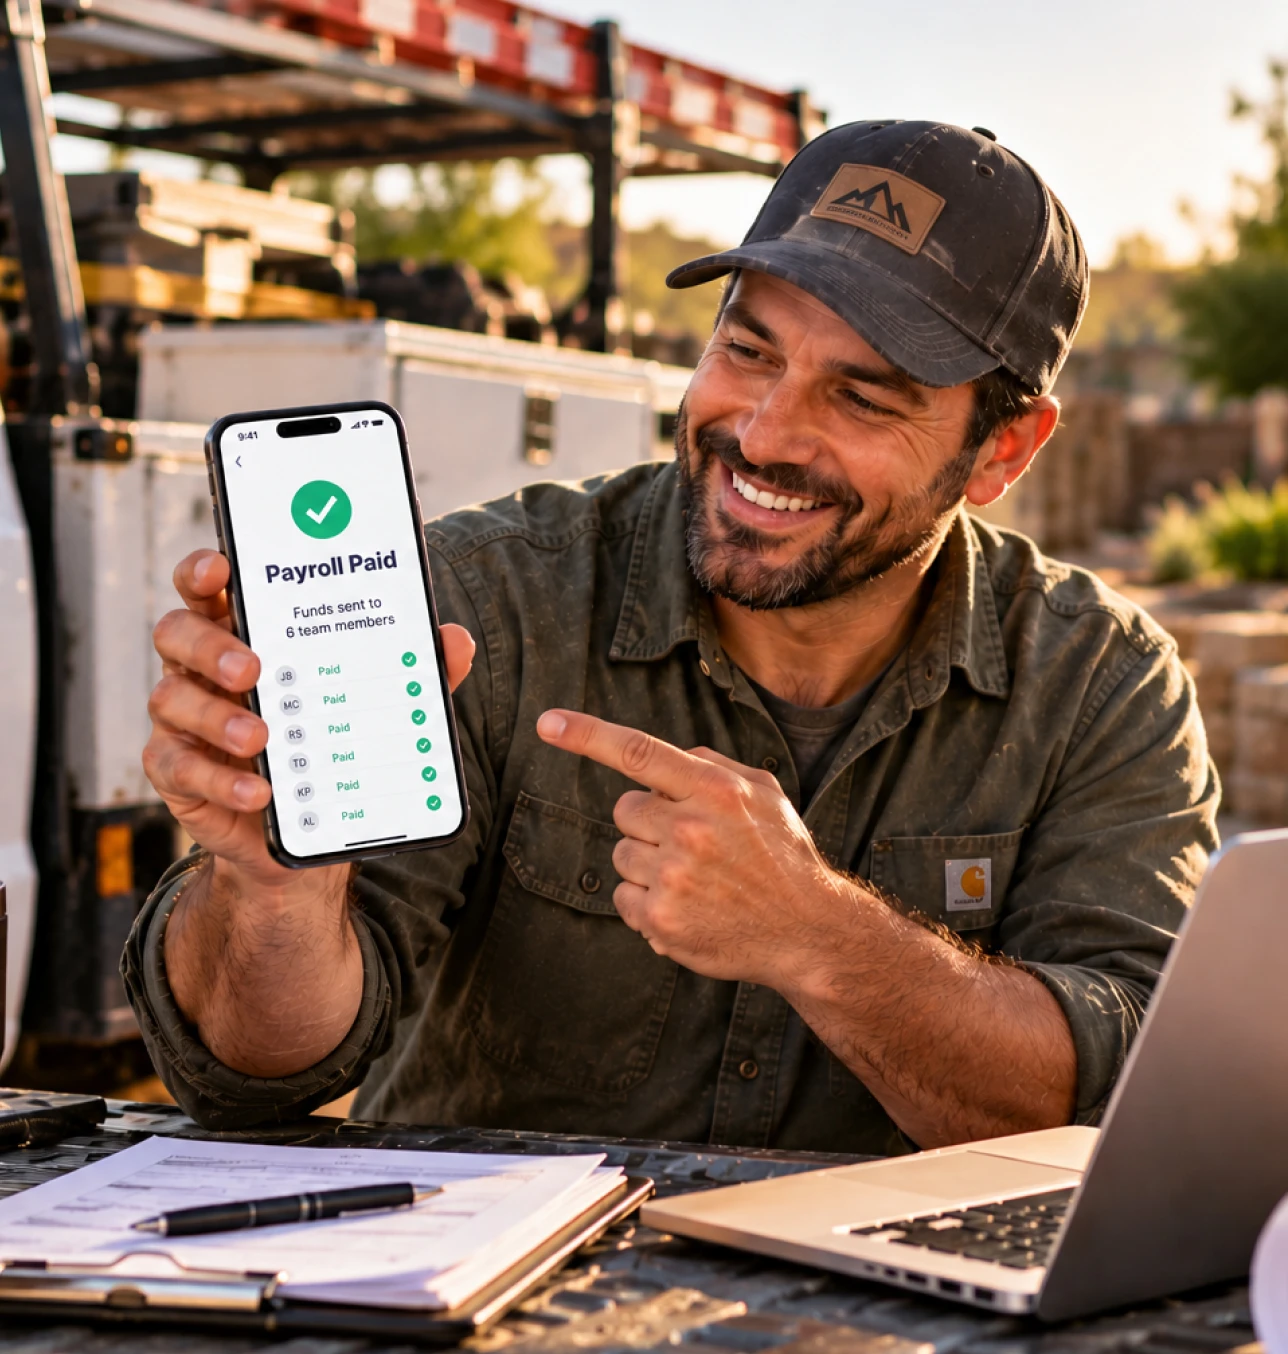
Payroll's due and the client hasn't paid yet
You pay your people every Friday, or every other Friday. Your clients pay on net-30 or net-45, and some of them pay late. So there are weeks when payroll's due and the money you've already earned is still sitting in an unpaid invoice. A heavy overtime week makes that gap bigger, and so does a new job you can't bill for yet.
Here's what you need to qualify
1+ year
$12K+
Your business also needs to be set up as an LLC or another registered entity, not a sole proprietorship.
Sounds like you? Checking takes a few minutes and won't touch your credit, so you'll know what you can draw before payday.
See what you qualify forPayroll line of credit vs. term loan vs. business credit card
| Features | Business Line of Credit | Term Loan* | Business Credit Card |
|---|---|---|---|
| How you access funds | Draw from an approved credit line when you need to cover payroll | Receive one lump sum upfront | Use the card for purchases up to the credit limit |
| What you pay for | Only the amount you draw | The full loan amount* | Purchases made on the card |
| Repayment | Each draw has a fixed daily, weekly, bi-weekly, or monthly repayment plan chosen upfront | Usually fixed payments over a set term* | Minimum monthly payments, with interest if a balance carries |
| Revolves? | Yes, the line revolves as you repay | No, it is a one-time loan* | Yes, available credit renews as you pay |
| Best for | Payroll, wages, and slow-paying clients | Larger one-time projects or major equipment purchases | Smaller purchases, subscriptions, or everyday expenses |
A term loan can fit one large purchase. A business credit card can fit smaller daily expenses. A business line of credit can fit ongoing needs, like payroll, wages, and slow-paying clients.
What owners usually draw for
Your crew did the work and the invoice is out. A draw keeps payday on time while the client's money is still on its way.
- Friday payroll while a big invoice is still unpaid
- Overtime from a rush job
- A payroll tax deposit that hits the same week as payday
- Paying a new hire before you can bill for their work
Draw funds when the business needs them. Repay daily, weekly, bi-weekly, or monthly. You choose the plan upfront. Keep your treasure chest available as you repay.
What a $22,000 payroll draw looks like

Say payroll this Friday is $22,000, and the invoice that would cover it is on net-45 and still unpaid. You draw $22,000 from your approved line.

Before you confirm, you pick how often to repay (daily, weekly, bi-weekly or monthly) and over how long. You'll see the total cost before you say yes.

If the client pays sooner and you pay the draw off early, there's no penalty for that. Paying off early can save up to 50% of remaining fees.

As you pay it down, that amount frees up on your line again for the next payroll. If you need the cash the same day, it's a $49 transfer fee.
It's a soft pull, and requests up to $30K get an instant decision.
What owners say on Trustpilot.
Loot funds small businesses across the US and ranks in the top 5% of lenders in its category for customer service.
Melody Brooke

“Having a way to draw funds as needed and then repay with no penalty, in fact, saving me money has helped my business grow.”
MBrooke Companies LLC
Daria WedVibes Media
“Would highly recommend Loot and their team, Maria & Manuela for business financing. Quick communication, immediate funding and clear instructions. Very useful for covering operational costs or need help while expanding.”
Dali Agency Inc
Payroll financing questions
Loot has no minimum FICO score requirement. Underwriting looks at real business cash flow, not just a credit score. For a Loot line of credit, we look for a business that's been open for a year or more. We also look for at least $12K a month coming into your business account. Your business should be set up as an LLC or another registered entity rather than a sole proprietorship. You won't need to put up any collateral and checking is a soft pull, so it won't affect your credit score.
No. It's a soft pull, so your score stays the same whether you're approved or not.
Under five minutes. You'll link your business bank account, and you won't have to upload any documents.
Requests up to $30K get an instant decision. Bigger ones can take a few more minutes, and if something needs a closer look, someone on our team reviews it. Once you're approved, you can have the money the same day for a $49 transfer fee, though timing can depend on your bank's processing times and cut-offs.
You'll see the total cost of a draw before you confirm it, and you only pay on what you draw, not your whole line. Getting the money the same day costs a $49 transfer fee. There's no penalty for clearing a draw ahead of schedule, and paying off early can save up to 50% of remaining fees.
Yes. Draw what this week's payroll needs and pay it back on the schedule you pick. A payroll tax deposit works the same way.
It works differently from a loan. With a term loan you get one lump sum and pay on all of it. With a Loot line of credit, you draw what this week's payroll needs, and as you pay it down you can draw again for the next one.
Make this week's payroll without emptying your account
If you've been open a year or more with at least $12K a month in business deposits, it takes under five minutes to find out how much you can draw.
You can get anywhere from $5,000 to $100,000, and you'll see the total cost of a draw before you take it.
No collateralInstant decisions on requests up to $30KIt's a soft pull, so it won't touch your credit score.
There are no hidden costs, and you only pay on what you draw.
For businesses open 1+ year with $12K+ a month in deposits
See what you qualify for