ROOFING CONTRACTORS • LINE OF CREDIT
Roofing contractor financing — keep every project covered
Loot offers roofing contractors an unsecured business line of credit from $5,000 to $100,000. Use it to cover materials, crews and equipment, or give your business the room to take on a larger project without draining the cash needed for everything else. Established roofing companies with 1+ year in business and $200K+ in annual revenue can check their options with a soft pull. Requests up to $30K get an instant decision, while larger requests may take a few more minutes.
 No collateral
 No hidden fees
 Same-day funding for $49
Roofing challenges: upfront costs, bigger jobs and payment timing
Roofing companies need steady cash flow to keep current jobs moving and say yes to bigger opportunities. Even when a customer pays a deposit, contractors may still need to cover materials, payroll, subcontractors, vehicles and equipment before the next payment arrives. When several projects overlap or a larger residential or commercial job requires more upfront, a full pipeline can put more pressure on cash flow, not less.
 Purchase materials before the next project payment arrives
- Add crews or subcontractors for larger and overlapping jobs
- Repair or replace essential equipment and vehicles
Where a roofing line of credit does the heavy lifting
Four moments when roofing cash flow needs backup — and how a Loot line of credit can help.

Purchase materials before the next payment arrives
Roofing projects require shingles, underlayment, flashing, fasteners and other materials before work can begin. Even with a customer deposit, the full cost may not be covered. A line of credit can help secure what the crew needs without pulling cash away from the rest of the business.

Take on a larger roofing project
A large roof replacement or commercial project can be good business, but it may also require a larger material order, additional labor and more equipment upfront. A line of credit can give roofing contractors the working capital to accept and mobilize the project without putting existing jobs under pressure.

Cover payroll and subcontractors
Employees and subcontractors still need to be paid when several projects overlap or progress payments haven't landed. A short-term draw can help cover labor without taking cash away from materials, vehicles or other scheduled work.

Handle equipment, vehicles and unexpected costs
A truck, trailer, lift or essential tool going down can affect more than one project. A line of credit can help cover repairs, replacement equipment or additional materials before the issue delays the schedule.
No Small Jobs: a day with Bonafide Roofing
See how a Loot line of credit helps Christian cover project costs and keep his roofing crew moving.
Watch their story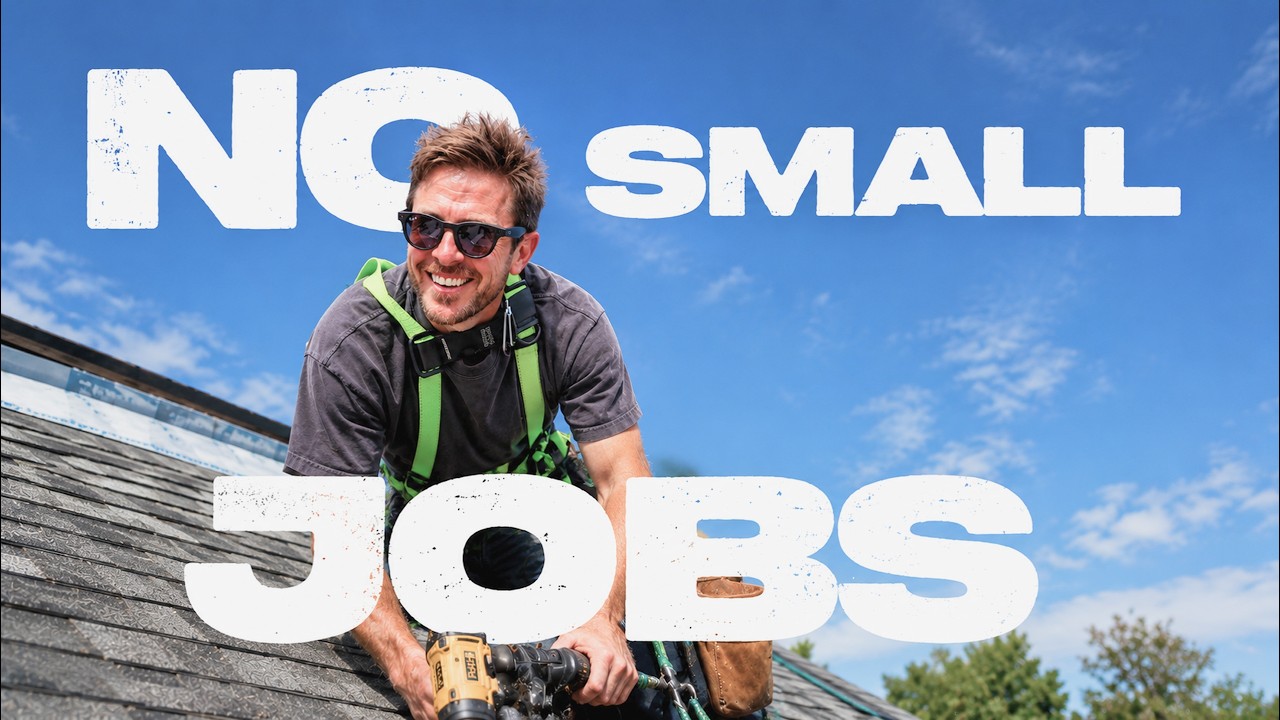
Why roofing contractors choose Loot
Loot is straightforward, transparent and built around how trade businesses operate. Projects overlap, upfront costs grow with the job and the next opportunity doesn't always wait for the last payment to arrive.

Clear and transparent pricing
See the exact cost and repayment terms before accepting a draw. No hidden fees or surprise changes after you move forward.

Fast online decisions
Apply in 5 minutes, link your business bank, and get a decision quickly — funds as fast as the same day.

Proven by business owners
"Knowing I have a line of credit I can count on gives me the confidence to take on bigger and more projects." — Christian, Owner of Bonafide Roofing.
How a Loot line of credit works for a roofing company

Say your roofing company wins a larger project and needs $25,000 for a bulk material order, additional crew costs and equipment before the next project payment arrives. You can draw $25,000 from your approved Loot line.

Before you confirm, you choose a fixed weekly repayment plan upfront, such as 16, 20, or 24 weeks. You see the total cost before you move forward.

If the project pays sooner than expected, there's no penalty for paying the draw off early. Pay off early and save up to 50% on your remaining fees.

As you repay, your line revolves — the funds become available again as you pay down the draw. Once approved, same-day funding is available for a $49 transfer fee.
Requirements for roofing contractor financing
To qualify with Loot, your roofing business needs:
1+ years
$200k+
None
Checking your options uses a soft credit inquiry, so it won't affect your credit score whether you're approved or not. Loot looks at your business cash flow, not only a personal credit score.
Roofing line of credit vs. term loan vs. business credit card
| Features | Business Line of Credit | Term Loan* | Business Credit Card |
|---|---|---|---|
| How you access funds | Draw from an approved credit line when your roofing business needs funds | Receive one lump sum upfront | Make purchases using the card |
| What you pay for | Only the amount you draw | The full loan amount* | Purchases and balances carried on the card |
| Repayment | Each draw has a fixed daily, weekly, bi-weekly, or monthly repayment plan chosen upfront | Usually fixed payments over a set term* | Minimum monthly payments, with interest if a balance carries |
| Revolves? | Yes, available credit returns as you repay | No, it is a one-time loan* | Yes, available credit returns as you pay |
| Best for | Materials, larger project costs, payroll, repairs and payment gaps | Large one-time purchases or major expansion | Smaller purchases and everyday expenses |
A term loan* may suit one large, planned purchase. A business credit card may work for smaller daily expenses. A line of credit can support recurring roofing costs and give the business more room when a larger project or overlapping schedule requires additional working capital.
What roofing contractors can use a line of credit for
- Shingles, tiles and metal roofing materials
- Underlayment, flashing, fasteners and supplies
- Upfront costs for larger residential or commercial projects
- Additional crews and subcontractors
- Employee payroll
- Trucks, trailers, lifts and fuel
- Equipment repairs and replacement tools
- Bulk material orders
- Insurance, licensing and operating expenses
- Customer and insurance-payment gaps
- Seasonal cash-flow changes
- Storm restoration and emergency work
Draw funds when the business needs them. Review the total cost and repayment plan before confirming, then regain access to your available credit as you repay.
Financing for residential roofing contractors
Residential roofing financing can help contractors cover materials, crews and equipment across repairs and full replacements. When several jobs overlap or a larger replacement needs more cash upfront, a line of credit can help keep the schedule moving.
Financing for commercial roofing contractors
Commercial projects may require larger material orders, additional labor and a longer period between starting the work and receiving each payment. A line of credit can help contractors mobilize the project while keeping enough cash available for the rest of the business.
Financing for roof repair and replacement companies
Repair and replacement businesses need to respond when a roof is damaged or no longer watertight. Financing can help cover materials, labor and equipment without waiting for another project payment to clear.
Financing for storm restoration contractors
Storm restoration companies can move from a normal schedule to a full pipeline quickly. A line of credit can help add crews, secure materials and begin approved work while customer and insurance payments are being processed.
Financing for specialist roofing installers
Metal, tile, slate and other specialist installations can require expensive materials and skilled labor upfront. A line of credit can help cover these project costs without draining the cash needed to run the rest of the business.
Financing for roofing equipment and vehicles
A grounded truck, damaged trailer or broken lift can quickly affect several projects. Contractors can draw for the expense, review the total repayment before confirming and pay the draw down early if project payments arrive sooner.
“Knowing I have a line of credit I can count on gives me the confidence to take on bigger and more projects.”
Roofing contractor financing FAQs
Yes. Roofing contractors can apply for a Loot business line of credit if they have 1+ year in business and $200K+ in annual revenue. Loot offers $5,000 to $100,000 with no collateral required.
Loot has no minimum FICO score requirement. Underwriting looks at real business cash flow, not just a credit score. Your roofing business still needs 1+ year in business and $200K+ in annual revenue to qualify.
Roofing contractors can get a decision in minutes, and same-day approval is standard. Once approved, same-day funding is available for a $49 transfer fee.
No. Checking eligibility with Loot is a soft pull. It does not impact your credit score, approved or not.
Yes. Roofing contractors can use a Loot line of credit for shingles, underlayment, flashing, lumber, and other materials needed before a deposit clears or a progress payment arrives. HVAC contractors working on the same new construction or renovation project often face the same material timing — both trades need to buy supplies before the builder's draw schedule catches up.
Yes. Roofing contractors can use a Loot line of credit for crew wages, subcontractor payments, and labor costs during busy season. Contractors that pick up work from solar installers needing roof prep or re-roofing before panel installation can cover those crew costs with a draw while the solar company's payment processes.
Contractors adding crews, buying equipment, or taking on larger commercial projects may benefit from a growing companies line of credit designed for businesses that are actively scaling.
Apply for roofing contractor financing today
Whether you need to keep current projects moving or want more room to take on a larger one, a business line of credit can give your roofing company working capital without draining the cash needed for everything else.
Get $5,000 to $100,000. Apply in under five minutes with a soft pull that won't affect your credit score. If approved, draw what you need, see the total cost before confirming and regain access to your available credit as you repay.
No collateralNo hidden fees Same-day funding for $49